Nordics
-
Nykredit Realkredit opened the Danish auction season on Monday with the sale of Dkr800m of two year covered bonds and Dkr7bn of one year bonds that are structured with a maturity extension trigger. Despite the triggers, the one year portion was oversubscribed multiple times and priced a long way inside swaps which Nykredit was very satisfied with.
-
OP Mortgage Bank returned for the second time this year on Wednesday to issue a €1bn five year covered bond. Though it was the tightest spread for a Finnish transaction seen in the last five years and priced with a negligible new issue premium, it still attracted a robust level of oversubscription.
-
Danske Bank’s first covered bond of the year offered an attractive spread relative to its Nordic peers, which made it a relatively straightforward sell. But even so, the final level was just one third of Danske’s differential against Sweden a year ago.
-
Danske Bank has mandated joint leads for a euro seven year benchmark, which is expected to be priced on Tuesday. The Danish bank had been expected to make a deal announcement some time ago, but decided to hold back after some tightly priced core covered bond deals failed to garner a sizeable book.
-
With a sizeable portfolio of variable rate mortgages, it makes sense for Stadshypotek to issue floating rate covered bonds, as this minimises interest rate risk and swap costs. Though the investor base for floating format covered bonds is still in its infancy, treatment of the asset class in bank liquidity buffers could soon be improved, and since FRNs are better suited for bank liquidity books, this is a market that could potentially deliver a substantial stream of demand.
-
Swedbank looks set to price the tightest non-German euro seven year benchmark covered bond in over five years, and with a negligible new issue premium. The transaction’s success drew on a confluence of positive factors.
-
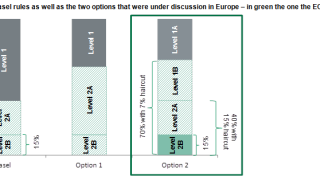
 Covered bonds rated AA- or higher will be elevated to a Level 1 asset in Liquidity Coverage Ratio (LCR) according to an internal document being circulated at the European Commission. This backs up a press release from the Danish government last Friday. The improved structural bid is most likely to affect bonds lower rated bonds previously ineligible for the LCR, said analysts.
-
The Norwegian Ministry of Finance on Tuesday defined what it considers a systemically important financial institutions, and said they should hold 2% more common equity tier 1 (CET1) than other Norwegian banks.
-
A new draft recommendation from the European Commission (EC) that appeared on the Danish government’s website on Friday says covered bonds which meet certain criteria can be considered extremely liquid assets and can fulfil up to 70% of bank liquidity buffers with a 7% haircut.
-
The Swedish Financial Supervisory Authority (FI) announced on Thursday that it will introduce higher capital requirements for four major Swedish banks. It also intends to activate a countercyclical capital buffer and has said it will increase the risk weight of mortgages from 15% to 25%, in line with the Riskbank’s recommendation last year.
-
The European Commission (EC) could be ready to lift the amount of covered bonds that can be used to fill Liquidity Coverage Ratio (LCR) requirements from a maximum of 40%, to a new higher limit of 60%, according to head of the Danish Mortgage Bankers Federation. The outcome could be known within a few days.
-
Credit sentiment is positive, and it seems unlikely that the European Central Bank would take anything other than an accommodative stance at next week’s policy meeting, but bankers are getting cautious that valuations are becoming overstretched, particularly in those markets which have until now been considered safe havens.