Europe
-
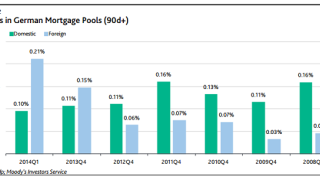
 Arrears in foreign assets backing German mortgage Pfandbrief increased by 40% in the first quarter of 2014, according to Moody’s, although the share of foreign mortgages in Pfandbrief cover pools is on a steady decline.
-
Banca Monte dei Paschi di Siena’s (MPS) covered bonds’ outperformed the market on Monday after Moody’s upgraded them from Ba1 to Baa3 following the European close on Friday. The new rating more than halves the capital charge as the bonds move into investment grade territory, opening up demand to a much larger investor base. This swell of new interest should ensure that MPS outperforms the market over the summer.
-
Well done Goldman Sachs, you’ve managed to devise a structure that has both the covered bond market and the ABS market talking at the same time. The covered bond market seems to have adopted the attitude that ‘imitation is the sincerest form of flattery, just don’t try to pass it off as a real covered bond’. The ABS market seem to have adopted an ‘anything the covered bond market can do..’ attitude.
-
Since Goldman’s FIGSCO (Fixed Income Global Structured Covered Obligation) trade hit the screen, capital markets commentators, The Cover included, have been scratching heads and stroking beards about what it actually is.
-
Goldman Sachs may have been hoping that it could get away with calling its newly structured triple recourse hybrid a covered bond. Though it is being marketed to covered bond investors, FIGSCO is clearly nothing like a classical covered bond. But Commerzbank, NIBC and NordLB all encountered controversy when they successfully issued innovative deals, suggesting the clumsily named acronym may be a success – especially in an environment of furious yield chasing and a shrinking triple A universe.
-
Austrian covered bonds were steady on Tuesday after a swathe of Moody’s senior downgrades hit covered bonds, leading bankers to say its methodology has serious weaknesses. Separately, Standard & Poor's upgraded €27bn of multi-Cédulas in a move which analysts said would have little impact and could soon be reversed. The fact multi-Cédulas have outperformed Austrian covered bonds all year is due to the other factors.
-
Nationwide opened books on Wednesday for the first post-crisis UK dual tranche covered transaction, and only the second from any jurisdiction this year. The success of the deal may establish dual tranche syndication as a benchmark for those issuers looking to raise size without compromising execution.
-
Germany will not accept the latest iteration of the European Commission’s discussion on the liquidity coverage ratio (LCR) calling for a minimum A- rating for eligibility into the putative class 1B. Non EEA issuers of bonds rated AA- or higher may get into level 2A. LCR talks will be extended, but not the implementation date.
-
BBVA announced that it will amortise two floating rate note retained Cédulas Hipotecarias on Wednesday. The move will increase overcollateralisation (OC) in its cover pool and could potentially result in a rating upgrade to the AA area with Standard & Poor’s, said Crédit Agricole analysts.
-
Nationwide has mandated leads for the third UK covered bond in euros this year. Though a firm decision on structure and tenor has not been taken, the issuer is testing appetite for a dual tranche offering that could involve the longest dated issuance seen in euros for years, to be launched Wednesday.
-
Berlin Hyp opened books on Monday for a deal which gave a positive litmus test on the condition of the core Pfandbrief market. The issuer may have been able to price a €500m deal at flat to Euribor but opted for a more liquid size at 1bp over mid-swaps in a move that was applauded but which shows resistance to sub-Euribor pricing has yet to be broken.
-
BPCE, Muenchener Hypothekenbank and Belfius Bank all launched 10 year covered bonds on Monday, underscoring the impression that investors are confident European yields could keep heading lower. Where once long end demand was dominated by real money, banks are now more dominant, a change that has been driven by the improved status of covered bonds in the liquidity coverage ratio.